Healthcare professionals

Tax planning for physicians, dentists, and other regulated professionals in Manitoba

School teaches you everything about your profession. It teaches you almost nothing about the financial decisions that follow. Healthcare professionals who incorporate pay as little as 9% on retained corporate income. Without the right structure, that same income is taxed at over 50% personally.

Serving clients in Manitoba and across Canada.

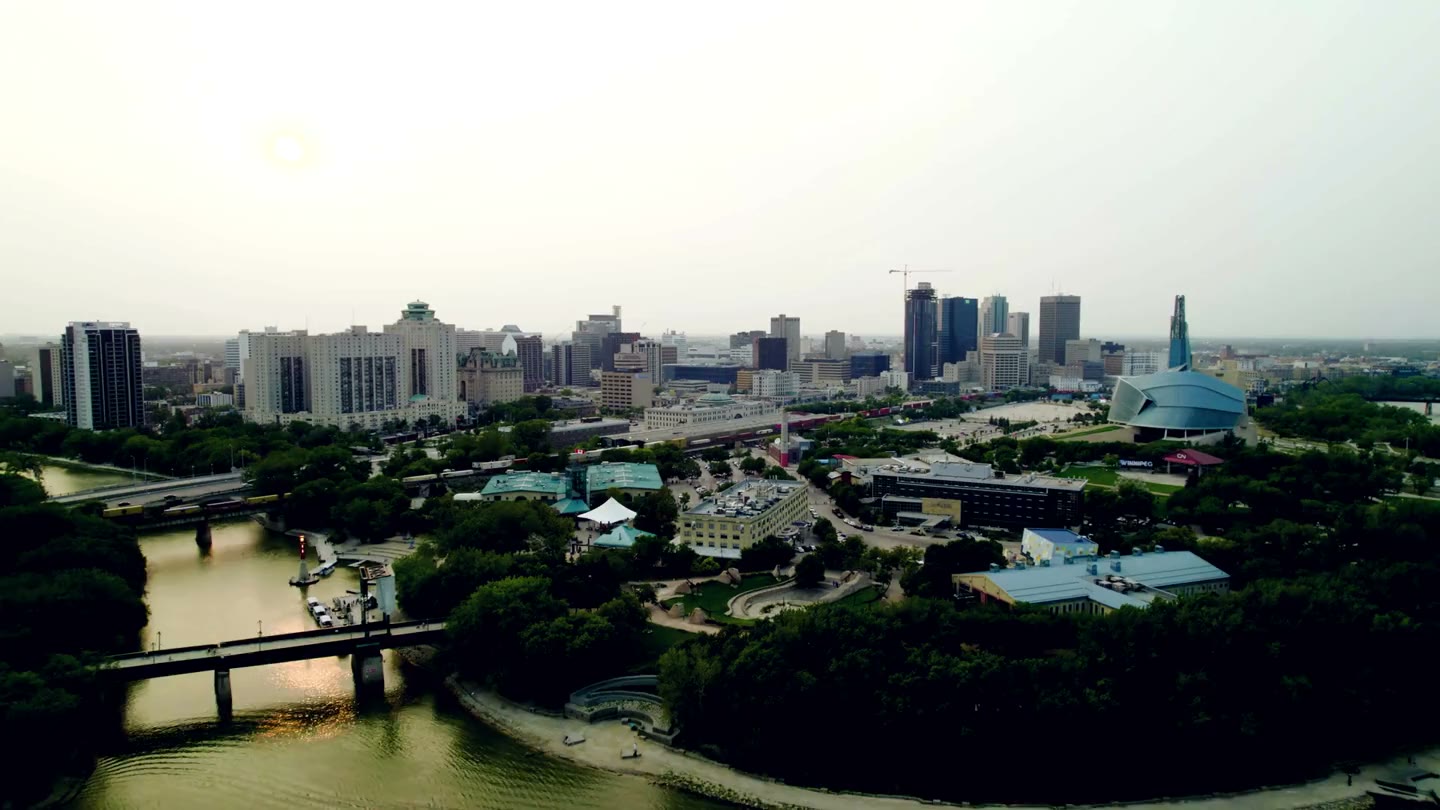
Aerial view of Winnipeg, Manitoba Evan speaks at UofM Medicine & Dentistry
Who we work with

Regulated healthcare professionals

Evan Barker regularly speaks to graduating classes at the Max Rady College of Medicine and the Dr. Gerald Niznick College of Dentistry at the University of Manitoba. Whether you are a resident planning your first professional corporation, a physician 10 years into practice looking to optimize your structure, an established professional thinking about what comes next, or a professional looking to sell their practice, this is the work we do every day. Not a side offering. The core of what we do.

  • Physicians & family doctors
  • Dentists & dental specialists
  • Veterinarians
  • Optometrists
  • Chiropractors
  • Pharmacists
  • Physiotherapists
  • Psychologists
  • Other regulated health professionals
9%

Manitoba's combined small business tax rate on the first $500,000 of active corporate income (varies by province).

9%Retained inside your professional corporation
50%+Taken personally at the top marginal rate

Why it matters

Why a professional corporation changes everything for healthcare professionals

As an unincorporated physician, dentist, veterinarian, or other regulated professional earning significant professional income, you pay personal tax on every dollar at over 50% at the top marginal rate. Through a professional corporation, the same income is first taxed at Manitoba's combined small business rate of just 9% on the first $500,000 of active business income. The gap between what you pay today and what you could pay inside a corporation is not a small planning detail. For a career spanning 25 to 30 years, it can represent a substantial amount.

Retained earnings inside your professional corporation can be invested, transferred to a holding company, or drawn down in lower-income years during retirement. The compounding effect over a career is substantial.

Incorporation is not only about the rate differential. It is about what you can do with the money that stays inside the corporation. A professional corporation becomes a long-term wealth-building vehicle, not just a filing obligation.
What we do

Services for physicians, dentists, veterinarians, and health professionals in Manitoba

01

Professional Corporation Setup

We work with you to ensure you incorporate when the time is right, and that your professional corporation is structured correctly from day one. We discuss share structure and initial compensation strategy so that everything is aligned prior to incorporating your professional practice.

02

Corporate tax strategy for professional corporations

Annual T2 preparation in the context of your full financial picture. Compensation structure, retained earnings, and corporate tax planning all working together to move you in the right direction.

03

Compensation planning: salary vs. dividends

Modelled to your specific situation every year. RRSP room, CPP, personal spending needs, spousal income, and long-term retirement plan all factored in to find the most efficient compensation structure.

04

Holding company setup

Dividends paid from your professional corporation to a holding company flow tax-free between Canadian corporations. This allows surplus income to be sheltered from personal tax rates, stay protected from liability risk, and invest with pre-tax dollars inside of a holding company.

05

Personal tax for health professionals

Your T1 prepared in the context of your professional corporation, holding company, investment accounts, and family situation. Dividend income, capital gains, and RRSP contributions all coordinated.

06

Income splitting and family compensation

Where the rules allow, structured correctly within the current TOSI rules and documented properly to be defensible under CRA review. Meaningful family tax savings are available when done right.

07

Individual Pension Plan (IPP)

A defined benefit pension inside your corporation with contribution room exceeding RRSP limits, particularly for health professionals over 40. We work with specialist partners to facilitate IPP setup for the right clients.

08

Health Spending Account (HSA) setup

Cover personal medical expenses through your corporation on a tax-deductible basis. One of the most consistently overlooked planning tools available to incorporated professionals. We can connect you with the right professional to set this up as part of your corporate structure.

For health professionals who own or are considering ownership in a clinic

Clinic financing, purchase & sale

Whether you're financing a clinic purchase or expansion, buying into an existing practice, or selling the clinic outright, we handle the valuation and financial modelling behind the deal and coordinate with your lawyer on the transaction itself.

Clinic structuring & associate compensation

Ongoing tax planning for clinic operations, GST issues, and structuring how compensation is split among associates or partners. We work with your lawyer on the agreements themselves and handle the tax and financial side.

For residents & students

Free personal tax returns for medical and dental residents and students.

If you are a medical resident/student or dental student with a straightforward return, no business income or rental properties, we will prepare your T1 at no charge. You are not yet incorporated, but the planning conversations that happen now shape the financial decisions you make later on. Let us get to know your situation before it gets complicated.

Book your free return
What our clients say

Trusted by healthcare professionals

Amazing personalized service. Such a great resource and support for professionals navigating their corporate structure and tax planning.
Dr. A. RicardPhysician, Manitoba
Started with Barker CPA as a second-year med student, even while studying out east in Ottawa, because I wanted to get ahead of my finances. I walked out of the first meeting actually understanding how physician incorporation works and when to do it. Now I feel 100% ready for when the time comes.
Jani C.Medical Student
Barker CPA has handled both my personal and corporate tax matters for some time now. They explain complex tax issues in plain language and are always available when I have questions. I would highly recommend them to any incorporated professional.
M. SokolowskiLawyer, Manitoba

Not sure if your current Manitoba professional corporation structure is working as hard as it should be?

Book a health professional consultation

Frequently asked questions

Questions about professional corporations for healthcare professionals

The questions we hear most from physicians, dentists, residents, and other regulated professionals.

Ask us directly
Should I incorporate as a physician or dentist?

Incorporation provides a meaningful tax advantage when your professional income consistently exceeds your personal spending needs. The key is that incorporation works best when you are not extracting all of your income personally. If you earn $200,000 and need $150,000 to live on, the remaining $50,000 retained inside the corporation is taxed at 9% in Manitoba rather than over 50% personally. The larger the gap between what you earn and what you need personally, the more meaningful the tax advantage becomes. The most common mistake we see is physicians and dentists incorporating but then pulling all of the corporation's cash out every year anyway, which defeats the purpose. The retained earnings can then be invested inside the corporation and drawn down strategically in lower-income years, during retirement. Whether incorporation makes sense depends on your income level, your personal spending needs, whether your profession is eligible, and your long-term financial goals.

Can veterinarians, optometrists, and chiropractors incorporate?

Many regulated health professions are eligible to incorporate as a professional corporation, including veterinarians, optometrists, chiropractors, pharmacists, physiotherapists, and psychologists. Eligibility is governed by your specific regulatory college and varies by province. Some professions gained incorporation rights relatively recently, so if you were told years ago that you could not incorporate, that answer may now be out of date. If you are a healthcare professional and you are not sure whether your profession is eligible, book a consultation and we will find out together.

What is Manitoba's small business tax rate for professional corporations?

Manitoba's combined small business tax rate is 9% on the first $500,000 of active business income earned through a qualifying Canadian-controlled private corporation. This combines the federal small business rate with provincial tax rates, and the rate varies by province. Compared to the personal top marginal rate of over 50%, the gap is substantial. For a physician, dentist, or veterinarian who earns more than they need personally and retains the surplus inside their professional corporation, the annual tax saving on that retained amount is significant. Compounded over a 25 to 30 year career, the difference in net wealth is material.

What is a Medical Professional Corporation?

A Medical Professional Corporation is a corporation owned by one or more licensed health professionals that earns income from the provision of professional services. Provincial legislation governs which professions are eligible and under what conditions. The MPC bills for professional services, receives income at the corporate level, pays the professional a reasonable salary or dividend, and retains the remainder inside the corporation at the small business tax rate. The professional must remain licensed and in good standing with their regulatory college for the corporation to operate.

Salary or dividends: which is better for a physician or dentist?

There is no universal answer, which is why this question comes up every year. Salary creates RRSP contribution room, CPP contributions, and a deductible expense for the corporation. Dividends are taxed at a lower personal rate but create no RRSP room or CPP entitlement. The right split for a healthcare professional depends on RRSP room goals, CPP reliance in retirement, personal spending needs, spousal income, and whether other retirement vehicles like an IPP are in place. Most incorporated healthcare professionals end up with a combination of both, calibrated annually to their specific situation and provincial tax rates.

What is the passive income grind-down and how does it affect my professional corporation?

The small business deduction, which gives your professional corporation access to the small business tax rate on its first $500,000 of active income, is reduced when your associated corporations collectively earn more than $50,000 in passive investment income in the prior year. For every dollar above $50,000, you lose $5 of small business limit. At $150,000 in passive income, the deduction is eliminated entirely. For healthcare professionals who have been accumulating retained earnings and investing them inside their professional corporation, this threshold can become relevant quickly. Strategies include moving investment assets to a holding company or restructuring how income is drawn from the corporation.

Should I set up a holding company alongside my professional corporation?

A holding company makes sense once your professional corporation is consistently generating more retained earnings than you need personally. The holding company receives dividends from the professional corporation on an inter-corporate tax-free basis, keeping those funds away from professional liability exposure. Inside the holding company you can invest in a diversified portfolio, hold real estate, or lend funds back to the professional corporation if needed. It also simplifies estate planning and can help manage the passive income grind-down. For most healthcare professionals with stable incomes above their personal spending needs, a holding company pays for itself within a few years.

When should a medical resident start thinking about incorporation?

Most residents are not yet eligible to incorporate because a professional corporation requires a full independent license to practice, which residents do not hold during training. However, the planning conversations should start well before graduation and at the end of residency. The financial decisions made in the first year of independent practice, including whether to incorporate, how to structure compensation, and whether to set up a holding company, have consequences that compound over an entire career. We offer complimentary personal tax returns for medical residents and dental students, and we regularly speak with students and residents at the University of Manitoba so that the structure is ready to implement the day they are eligible. There is no better time to start the conversation.

What expenses can I deduct through my professional corporation?

Legitimate business expenses incurred to earn professional income are deductible at the corporate level for professional corporations. This typically includes professional liability insurance, regulatory college fees, continuing medical or professional education, professional memberships and dues, office or clinic expenses where you are not reimbursed, accounting and legal fees, and reasonable home office expenses. The corporation can also cover a Health Spending Account, allowing personal medical expenses to be paid through the corporation on a tax-deductible basis. Expenses that are personal in nature are not deductible regardless of whether they are paid through the corporation.

What happens to the money inside my professional corporation when I retire?

The wind-down of a professional corporation is a planning exercise that should begin well before your retirement date. Options include drawing down retained earnings gradually over several years as lower-income dividends in retirement, transferring assets to a holding company before winding down the professional corporation, using the Lifetime Capital Gains Exemption on the sale of qualifying shares, or continuing the holding company indefinitely and drawing from it on your own schedule. The right approach for a healthcare professional depends on how much is inside the corporation, personal income in retirement, estate planning goals, and whether the shares qualify for the Lifetime Capital Gains Exemption. Planning for this should begin at least five to ten years before you stop practicing.

Do you serve physicians and healthcare professionals across Canada?

We operate as a fully digital, remote-first firm and serve incorporated physicians, dentists, veterinarians, and regulated health professionals across Canada. That includes clients in British Columbia, Alberta, Saskatchewan, Ontario, and the Atlantic provinces. Everything we do, including professional corporation setup, T1 and T2 preparation, compensation planning, and day-to-day communication, happens online. Your location does not affect the quality or responsiveness of the service. We are currently not offering services to clients residing in Quebec.

How does maternity or parental leave affect my professional corporation?

This is one of the most common planning questions we get from physician and dentist clients. During a parental leave, no professional income flows through the corporation, but the corporation continues to exist and carries its own administrative costs including accounting fees and corporate filing requirements. The good news is that a parental leave is often one of the best times to draw dividends from your retained earnings at a lower personal tax rate, since your total income for the year is likely reduced. It can also be a valuable window to review your corporate structure and ensure everything is optimized before you return to practice. Planning ahead before your leave starts can make a meaningful difference in how efficiently you use this period.

Can I split income with my spouse through my professional corporation in Canada?

The Tax on Split Income (TOSI) rules significantly restricted income splitting with family members for incorporated professionals. Under the current rules, dividends paid to a spouse from your professional corporation are generally subject to the highest marginal tax rate unless the spouse meets specific criteria, most commonly actively working in the business for an average of at least 20 hours per week. Once your spouse reaches age 65, income splitting becomes available regardless of their involvement in the practice. Non-voting shares for family members remain part of many corporate structures, but the tax benefit is limited for most physicians and dentists until retirement age. The right answer depends on your specific family and practice situation and is worth reviewing carefully with your accountant.

Ready to talk through your situation?

Whether you are just starting to think about incorporating, already established and looking for a second opinion, or planning the wind-down of your professional corporation, book a consultation and we will walk through where you are and the next steps together.